Disappearing Barclays Cards Offer Opportunity for Quick Addition of American/ Hawaiian Miles
Frank McBride • April 21, 2025
Soon-to-be discontinued cards yield solid signup bonuses with minimal spending
Barclays offers several co-branded travel cards, but two of them will be disappearing soon. The American Aadvantage Aviator Red MasterCard is being discontinued as Barclays lost out in a new agreement between American and Citi to give Citi exclusivity in offering a co-branded American credit card. The Hawaiian Airlines World Elite Mastercard will be discontinued at some point because Hawaiian has merged with Alaska Airlines (which offers a co-branded card issued through Bank of America).
Although these cards’ days are numbered, both are still available and offer an excellent opportunity to pick up generous signup bonuses.
Barclays American Aadvantage Aviator MasterCard
This card has been part of an American Airlines “double play” that both Ms. Optimizer and I have used. It is also a quick and inexpensive way to add Aadvantage miles to your account.
The current sign-up bonus offer is 60,000 miles after you have paid the $99 annual fee and made your first purchase on the card in any amount. In other words, you could get 60,000 miles added to your Aadvantage account in just one billing cycle after spending a few dollars.
Like many airline cards, this one offers a free checked bag as well as early boarding when flying American.
The bonus structure for spending is not particularly exciting as you get a 2X bonus for American Airlines purchases and one mile per dollar for all other purchases.
Once Barclays gets dropped as American’s partner, my understanding is that this product will get converted to a Citi product. Any American miles you earn will, of course, remain in your account.
Barclays Hawaiian Airlines World Elite MasterCard
Although Alaska and Hawaiian Airlines have merged, Hawaiian miles can still be earned and this card is still being offered (for now).
The current offer is 60,000 Hawaiian miles after spending at least $2,000 in the first 90 days after approval. The annual fee is $99.
The bonus spending structure includes a 3X bonus for Hawaiian Airlines purchases and a 2X bonus for spending on dining, gas, and grocers. One benefit is a $100 companion ticket discount for travel between Hawaii and the continental US at each one year anniversary.
I am not certain what will become of this card but Hawaiian miles will be converted to Alaska miles at some point in the future.
Risks of Applying for These “Short Termer” Cards
From what I understand, there is no risk to the 60,000 mile sign-up bonuses assuming you complete the minimum spending in a timely fashion. American miles stay in your Aadvantage account whether coming from a Barclays product, a Citi product, flying American, or other activities. Hawaiian miles will be converted to Alaskan miles as the integration of the Hawaiian and Alaskan programs is completed.
Less is known about your status as a cardholder. Does the card become another Barclay product that no longer generates American/Hawaiian miles? Does the card get converted to a Citi or Bank of America product? If you are moved to another card issuer, are you automatically approved or do you have to reapply?
Another risk is the temptation to “earn and churn” with these cards. I like to think of the points and miles game as a long term and sustainable hobby and counsel clients to “play nice” with issuers rather than grabbing bonuses and cancelling the card after one year. Potential applicants should determine if they want to build a relationship with Barclays, especially as Barclays offers other co-branded travel cards they might want in the future including JetBlue, Emirates, Frontier, Lufthansa, Breeze, Wyndham, and Carnival.
But, if either card makes sense for you, it is better to apply sooner rather than later.
Because these cards might play an adjunct role in your points and miles pursuit, it is important to develop a comprehensive program to make sure you are getting the most free travel from your routine credit card spending. When we design a custom Travel Rewards Optimizer plan for you, we take your travel goals, travel habits, spending patterns, and preferences into account. We want to ensure that the cards we recommend for you can quickly generate free travel and provide relevant benefits while keeping your annual card fees under control.
We are ready to help you turn your routine credit card spending into the travel of your dreams.
In case you missed them, here is your "one-stop shopping" for posts from the past week. For some, recent changes with the Resy restaurant reservation platform might limit dining options when using the credit. Learn more here . Perhaps your next US domestic award flight should be booked through . . . Air France. Check out why . The Amex Platinum card might have the highest annual fee for mass marketed cards. Find out if the benefits are worth it for my household here . Hope you have a great Labor Day weekend!! We are ready to help you turn your routine credit card spending into the travel of your dreams.
A walk through one household's use of the Amex Platinum card
For some domestic flights, Air France might save transferable miles
Recent changes in the Resy reservations platform might limit use of the Amex dining credit
Changes are a mixed bag but Hyatt regulars won't be happy
Some good news in points and miles (and one warning)
A change in favor of airline passengers (for a change)
The Autograph Journey's transfer partner list grows slowly but steadily
Points and miles free up the travel budget for pilsner, paprika, and pastizzi*
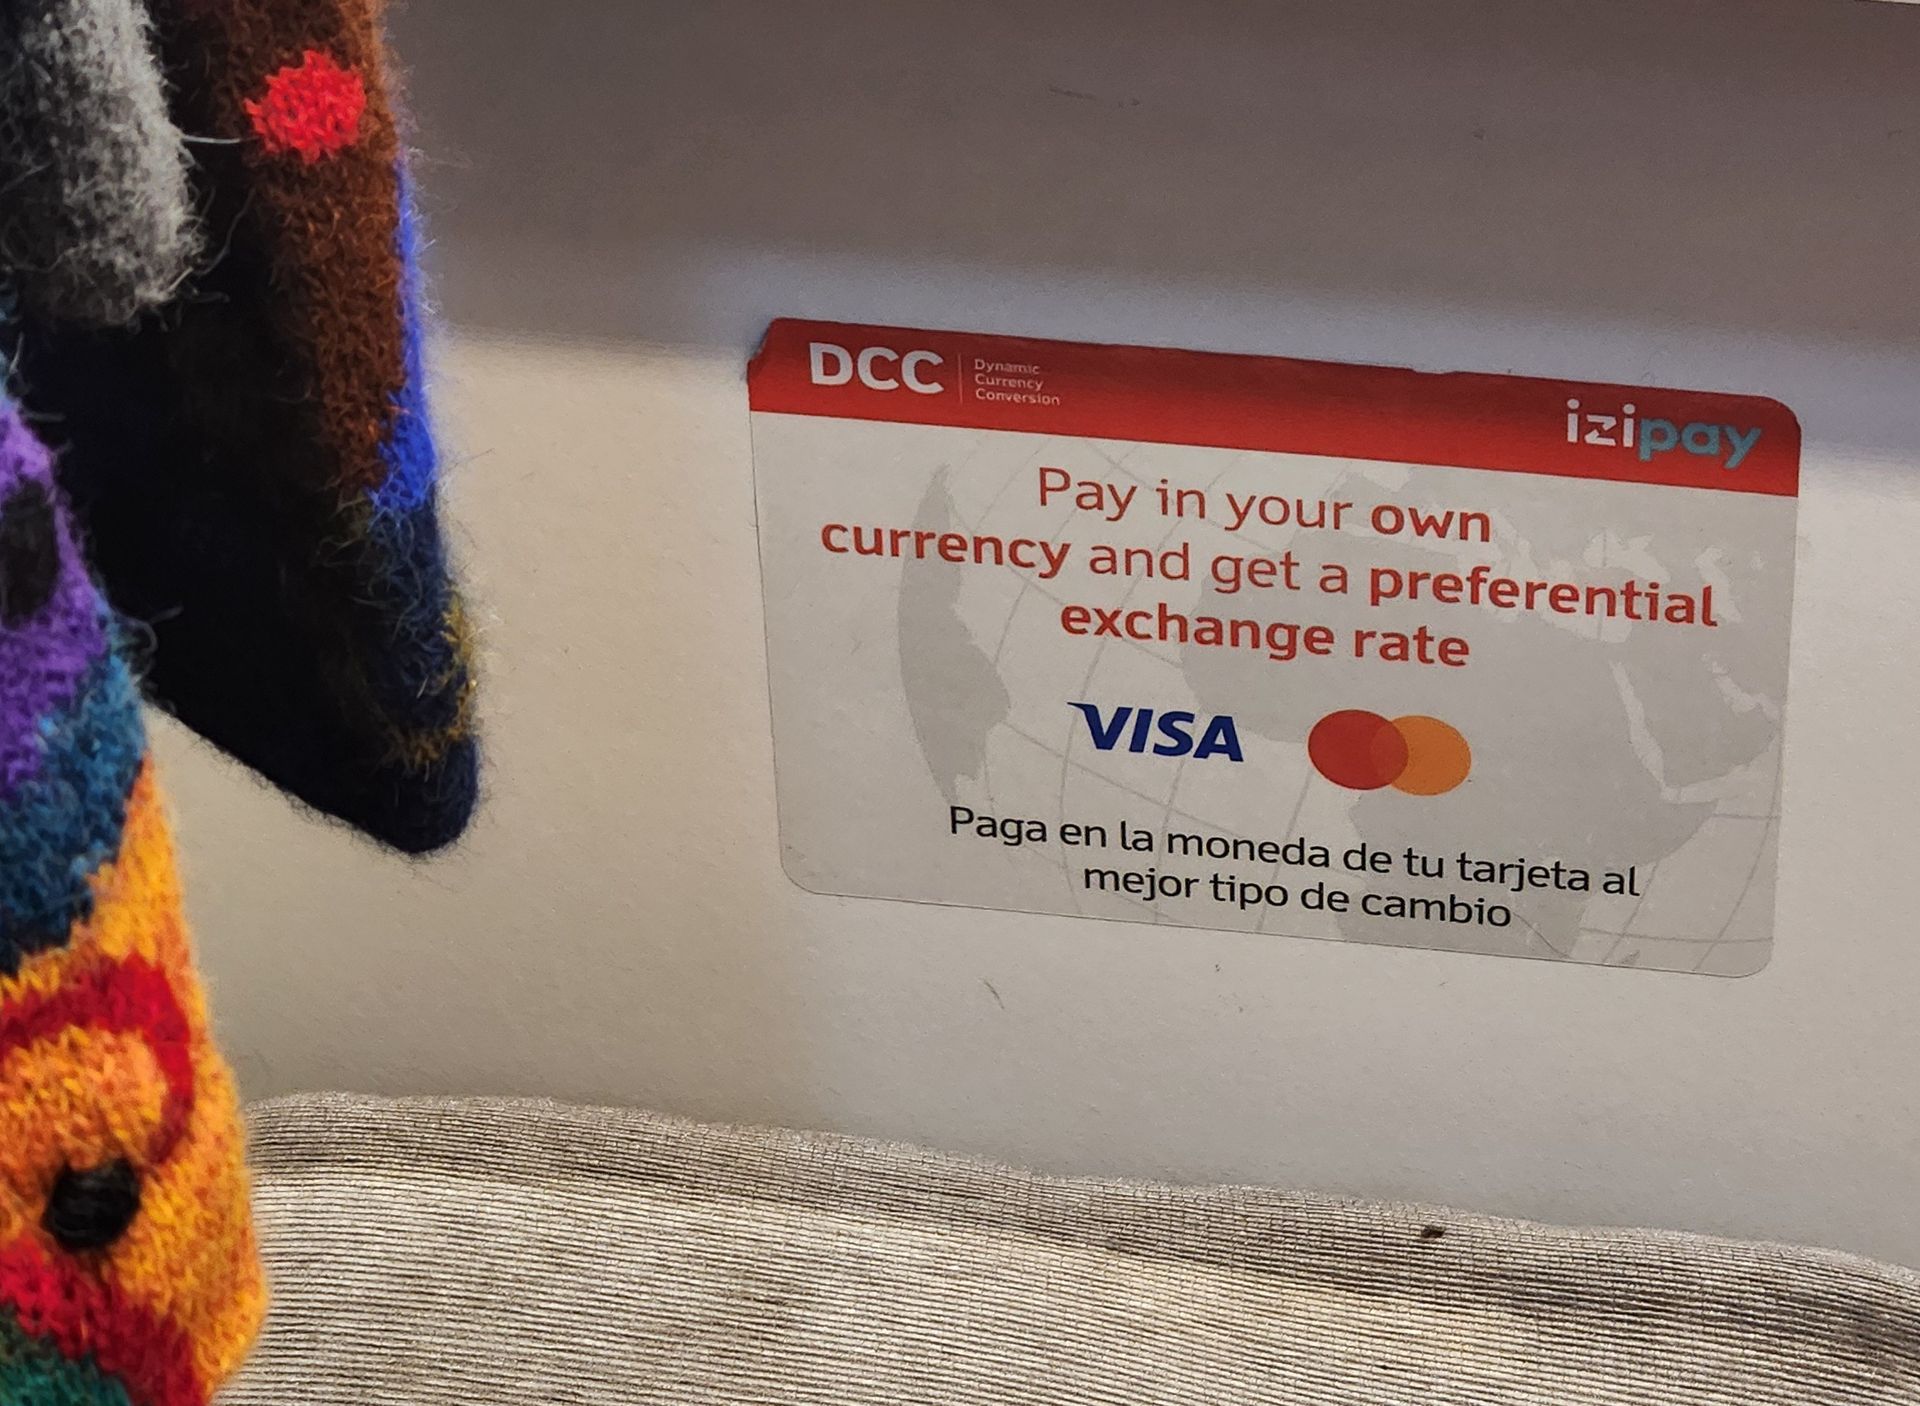
As the summer travel season approaches, this is a friendly reminder to avoid "dynamic currency conversion" (DCC) when making credit card purchases outside of your home country. DCC gives you the option of selecting a payment amount in your home currency rather than in the local currency. Typically, when presented with a credit card reader at a shop or restaurant, the touch screen will show purchase amounts in the local currency and in US dollars (for those with American credit cards) and you have the opportunity to choose. I have been seeing these “offers” for several years now and have learned, after doing a little mental math, they are almost always a bad deal for the purchaser. When presented with a credit card reader, I always choose to pay the amount shown in local currency rather than the amount shown in US dollars. During a recent trip, I was making purchases in Euros, Hungarian Forints, and Czech Korunas. From what I could tell, the option of paying in dollars inflated the cost of the purchases around an average of five percent (5%). Once, a card reader screen acknowledged that making the purchase in dollars added an eight percent (8%) fee. Even a credit card with a foreign transaction fee (which you should avoid using when traveling abroad) would have added only three percent (3%) to the tab. Currency games aside, Visa and MasterCard offer reasonable exchange rates when you choose to pay in the local currency. Upon returning home, our credit card statements showed exchange rates that were quite close to market rates. It is reasonable and fair for the credit card issuers make a fraction of a percent here and there as they are performing a service and accepting currency risk (although very briefly). But, claiming to offer a “preferential” rate to pad their bottom line is disingenuous. Because exchange rates are reasonable, using credit cards while traveling abroad is still worthwhile for a points and miles program as long as you avoid cards with foreign transaction fees. Travel oriented cards can offer 2X and 3X spending bonuses for transportation and restaurants to give you a leg up on saving money and accumulating points or miles for your next vacation.