Flying “Air France” Domestically in the United States

Frank McBride • August 28, 2026

For some domestic flights, Air France might save transferable miles

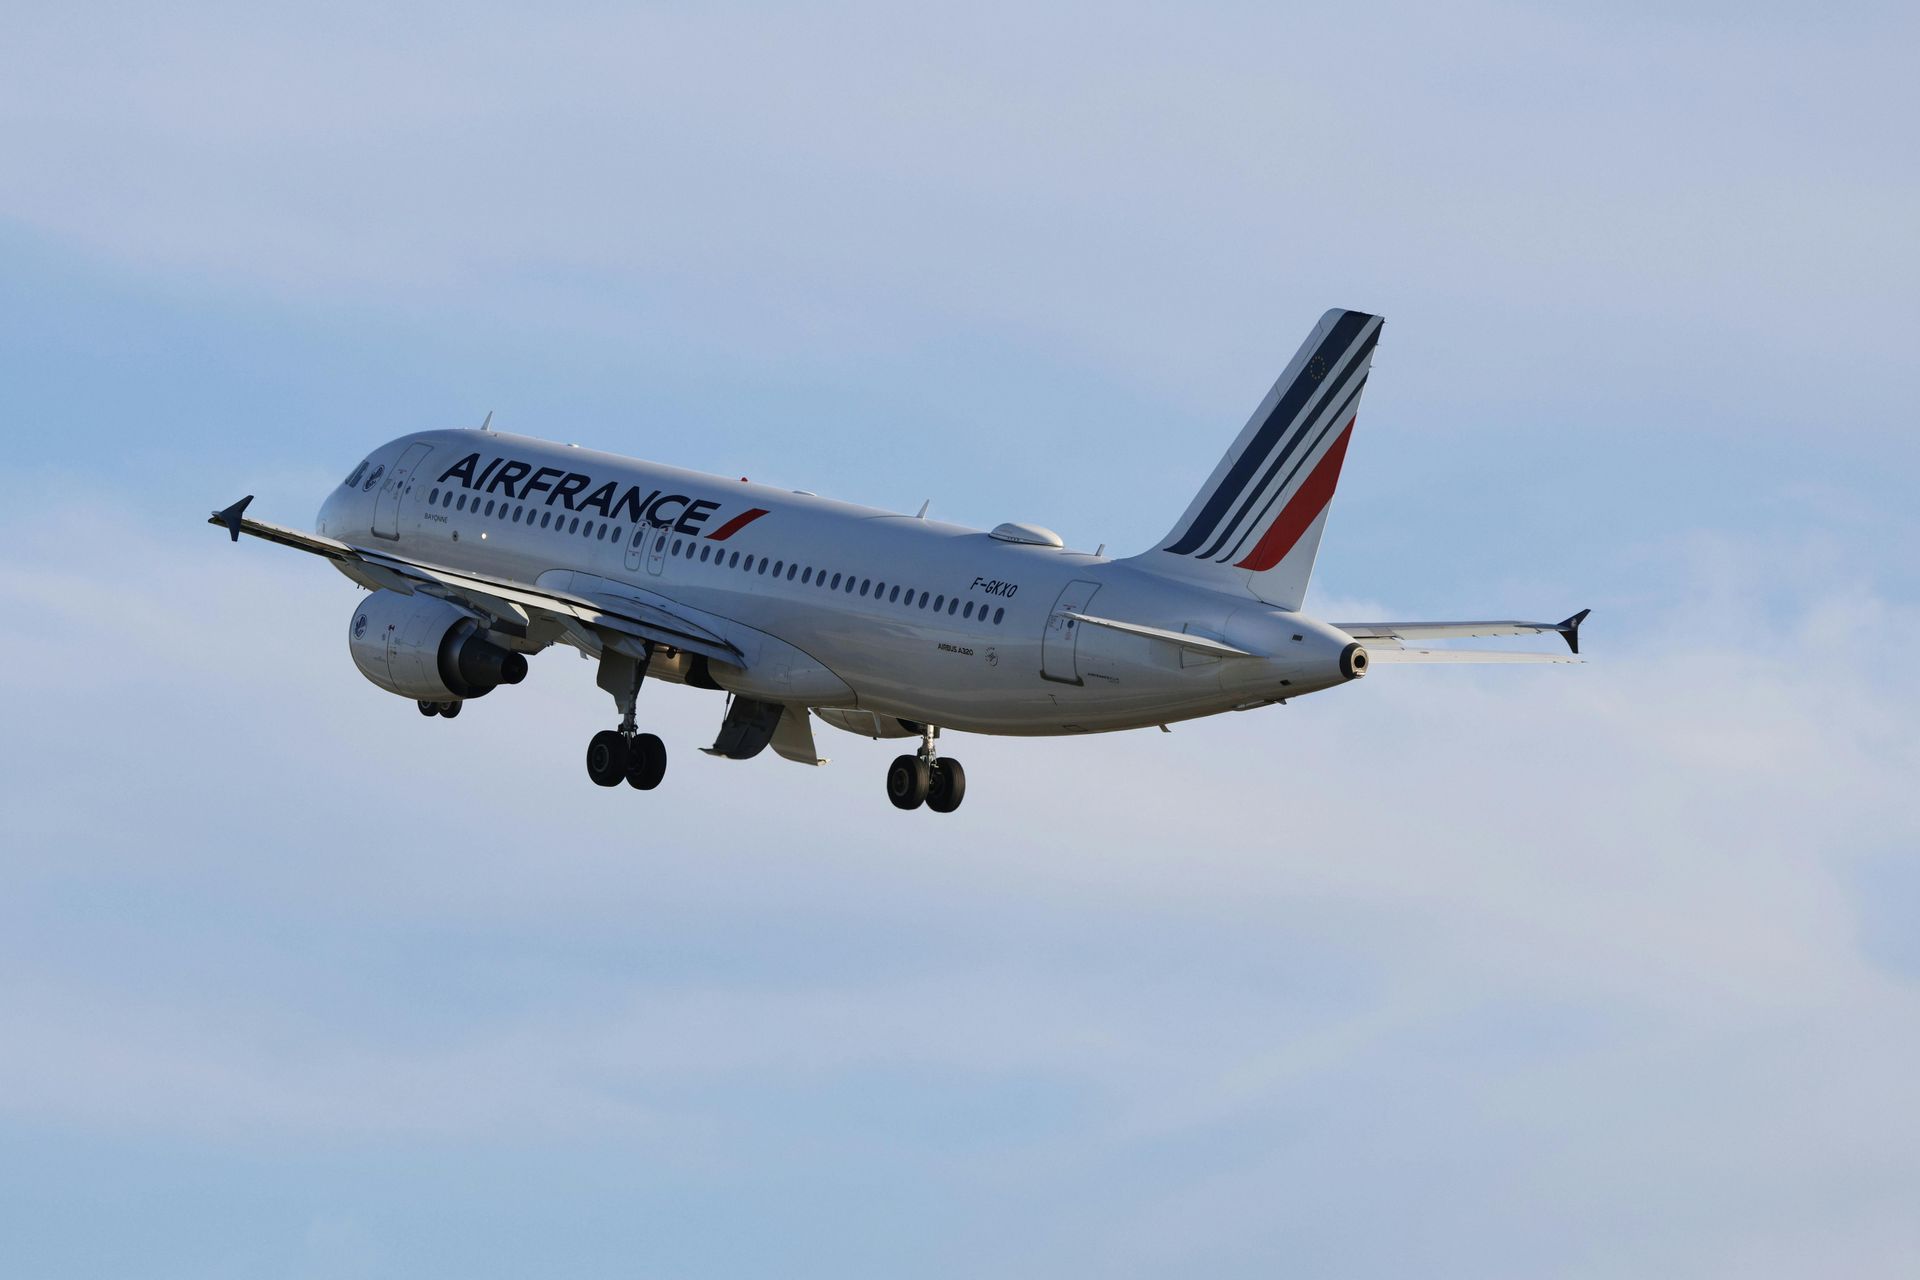
Recently, I flew to Atlanta with the Optimi-daughter to visit the Georgia Aquarium. We participated in the aquarium’s “Sea Otter Encounter” (they were otter-ly adorable). This was a day trip, and I used points to book our domestic, non-stop flight with . . . Air France.


Of course, we did not fly on an Air France airplane, but rather on a Delta flight that code shares with Air France. Here is my rationale for booking this round trip with Air France instead of Delta.


Delta wanted 40,400 miles for the two round trips plus $22.40 for the TSA fees that you cannot avoid even when taking award flights. However, Air France required just 28,000 miles plus $71 in fees. Both airlines would let me transfer American Express points to their frequent flyer programs at a 1:1 ratio. Although the additional cash cost of booking with Air France instead of Delta was $49, I was able to conserve 12,400 American Express points. Since it is easy to get at least one cent per point in value out of Amex points, the minimum value of the saved miles was about $125. However, based on prior transfers of Amex points to airline partners, I would be likely to get even more value from the saved miles.


Making reservations on the Delta flight through Air France was reasonably straightforward. In addition to booking the flight, I was able to select seats. Twenty-four hours prior to flight time, I received a message from Delta letting me know I could check in for the flight and the boarding pass I printed out at home was a Delta boarding pass. There was no impact on my ability to use the Delta SkyClub. The only wrinkle was that, even though Delta was communicating with me about check-in, the flight did not appear under “My Trips” on my Delta account online or the Delta app. But overall, we had a standard Delta experience.


I don’t see much downside to reserving domestic Delta flights with Air France if you have Air France miles or transferable points available. I will point out that Air France offers a limited number of domestic US options so you cannot book any Delta flight through Air France. Sometimes I find flights that work and that I can fly for fewer points while sometimes there is either lack of availability of good flights or the points/cash cost does not justify booking with Air France over Delta. It is also important to keep in mind that, if problems arise with a flight, the “Air France” passenger might not be a high priority. As “Air France” passengers, we boarded with Group 7, an indication of being lower priority passengers.


When we create a Travel Rewards Optimizer plan for our clients, we take the kinds of information shared in this post to help you get to free and reduced cost travel as quickly as possible. The points and miles world is a filled with opportunities and pitfalls, but we keep an eye on this constantly changing landscape so you can spend your time planning your next vacation.


We are ready to help you turn your routine credit card spending into the travel of your dreams.
By Frank McBride • September 21, 2026
Chase is about to devalue Chase UR point to World of Hyatt point transfers
By Frank McBride • September 4, 2026
In case you missed them, here is your "one-stop shopping" for posts from the past week. For some, recent changes with the Resy restaurant reservation platform might limit dining options when using the credit. Learn more here . Perhaps your next US domestic award flight should be booked through . . . Air France. Check out why . The Amex Platinum card might have the highest annual fee for mass marketed cards. Find out if the benefits are worth it for my household here . Hope you have a great Labor Day weekend!! We are ready to help you turn your routine credit card spending into the travel of your dreams.
By Frank McBride • September 3, 2026
A walk through one household's use of the Amex Platinum card
By Frank McBride • August 27, 2026
Recent changes in the Resy reservations platform might limit use of the Amex dining credit
By Frank McBride • June 25, 2026
Changes are a mixed bag but Hyatt regulars won't be happy
By Frank McBride • June 5, 2026
Some good news in points and miles (and one warning)
By Frank McBride • May 29, 2026
A change in favor of airline passengers (for a change)
By Frank McBride • May 19, 2026
The Autograph Journey's transfer partner list grows slowly but steadily
By Frank McBride • April 29, 2026
Points and miles free up the travel budget for pilsner, paprika, and pastizzi*
By Frank McBride • April 23, 2026
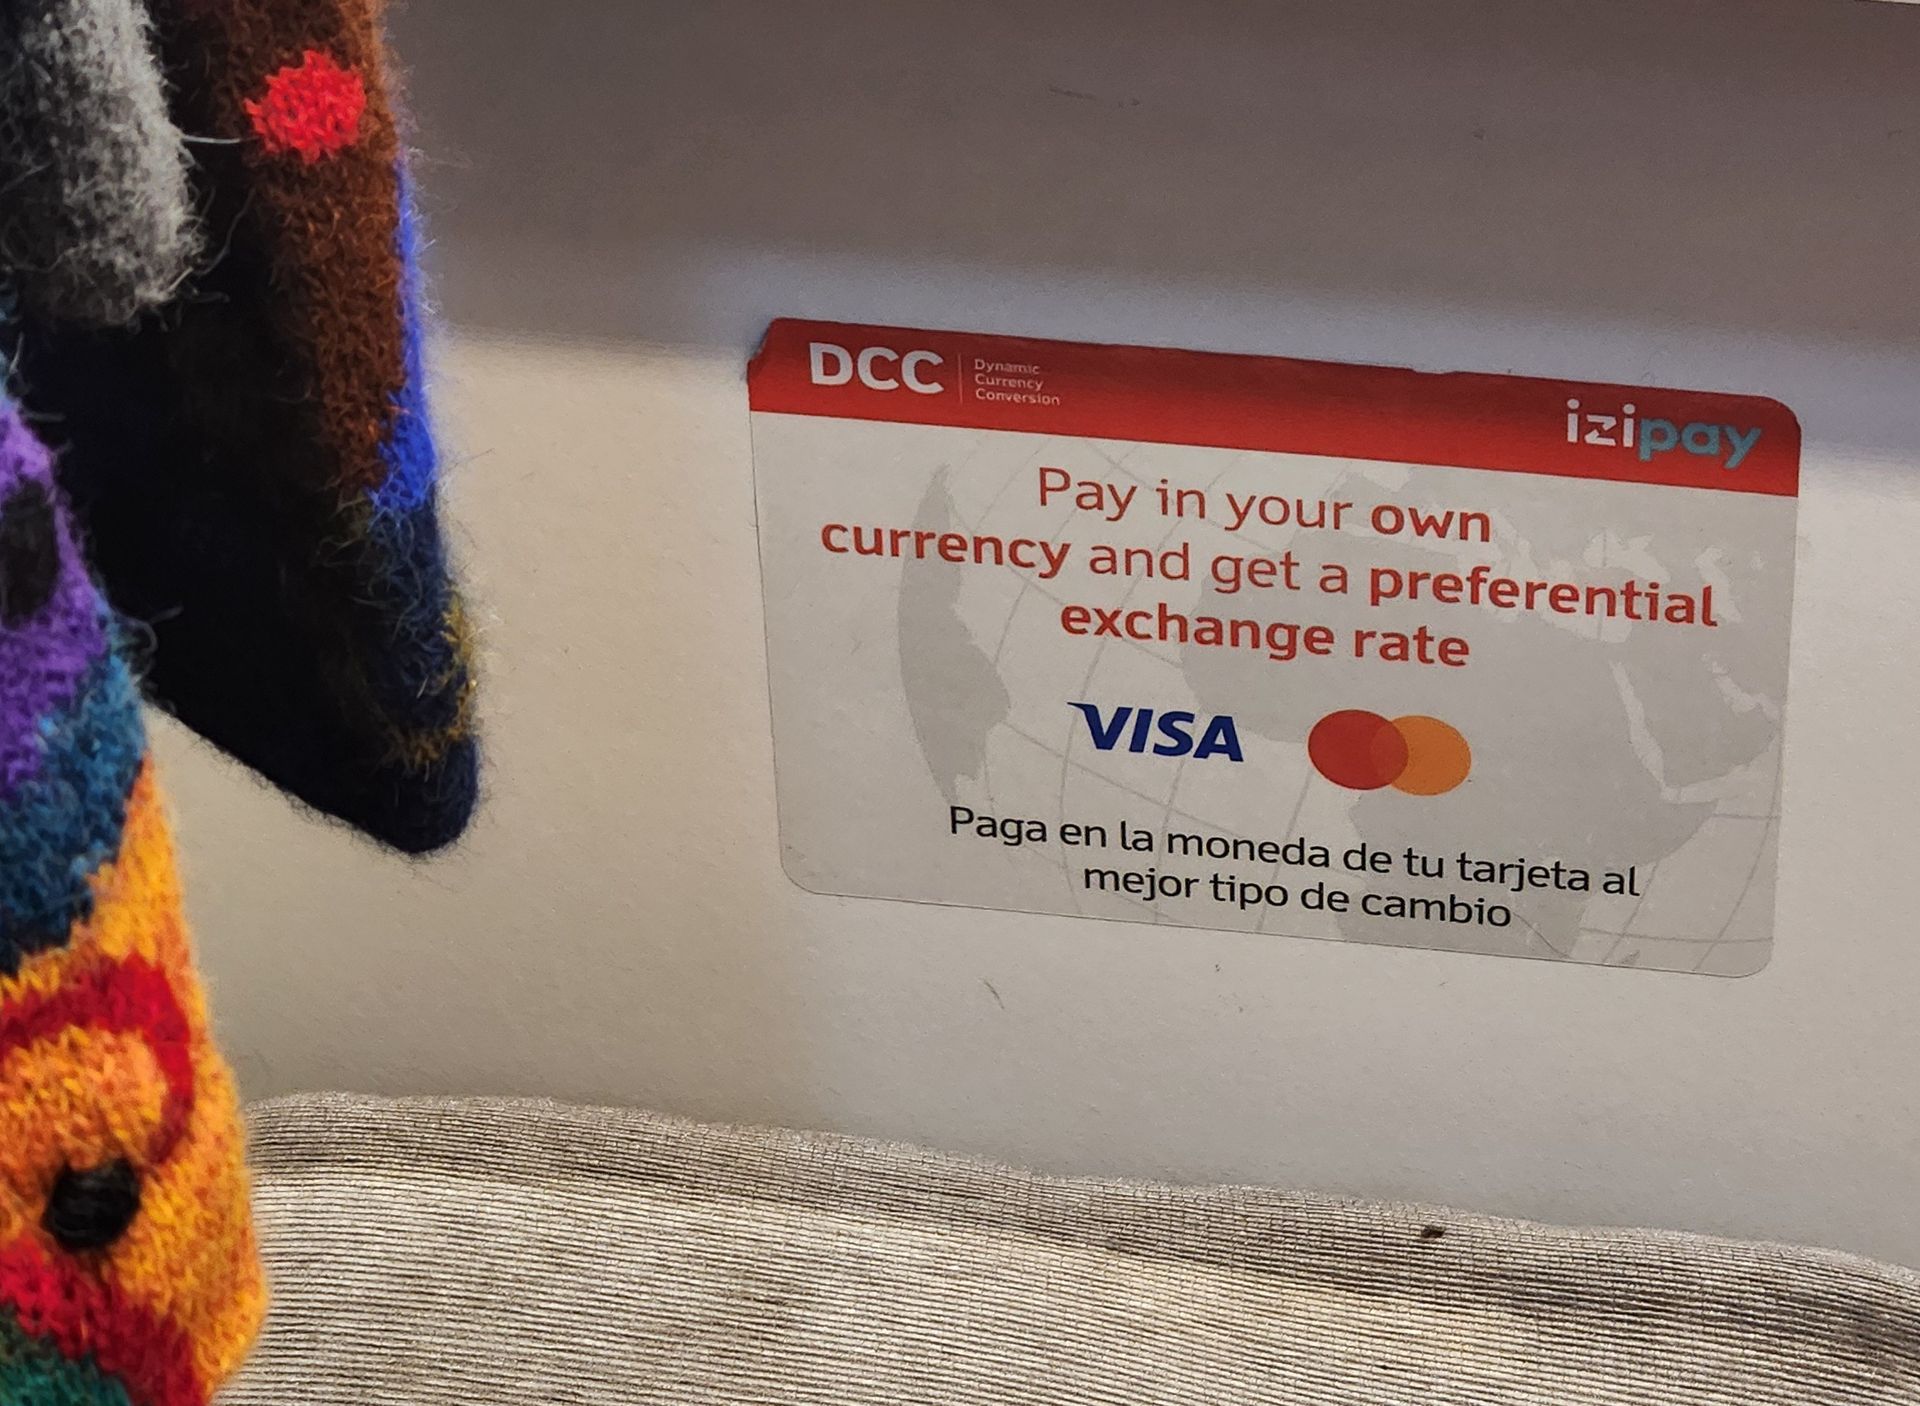
As the summer travel season approaches, this is a friendly reminder to avoid "dynamic currency conversion" (DCC) when making credit card purchases outside of your home country. DCC gives you the option of selecting a payment amount in your home currency rather than in the local currency. Typically, when presented with a credit card reader at a shop or restaurant, the touch screen will show purchase amounts in the local currency and in US dollars (for those with American credit cards) and you have the opportunity to choose. I have been seeing these “offers” for several years now and have learned, after doing a little mental math, they are almost always a bad deal for the purchaser. When presented with a credit card reader, I always choose to pay the amount shown in local currency rather than the amount shown in US dollars. During a recent trip, I was making purchases in Euros, Hungarian Forints, and Czech Korunas. From what I could tell, the option of paying in dollars inflated the cost of the purchases around an average of five percent (5%). Once, a card reader screen acknowledged that making the purchase in dollars added an eight percent (8%) fee. Even a credit card with a foreign transaction fee (which you should avoid using when traveling abroad) would have added only three percent (3%) to the tab. Currency games aside, Visa and MasterCard offer reasonable exchange rates when you choose to pay in the local currency. Upon returning home, our credit card statements showed exchange rates that were quite close to market rates. It is reasonable and fair for the credit card issuers make a fraction of a percent here and there as they are performing a service and accepting currency risk (although very briefly). But, claiming to offer a “preferential” rate to pad their bottom line is disingenuous. Because exchange rates are reasonable, using credit cards while traveling abroad is still worthwhile for a points and miles program as long as you avoid cards with foreign transaction fees. Travel oriented cards can offer 2X and 3X spending bonuses for transportation and restaurants to give you a leg up on saving money and accumulating points or miles for your next vacation.