American Express Platinum Card Hikes Fees for Authorized Users

Frank McBride • September 11, 2023

Several weeks ago, I wrote about how American Airlines increased annual membership fees and one day pass costs for their Admirals Club lounges. Additionally, the annual fee for the Citibank Aadvantage credit card that includes Admirals Club lounge access has also increased.

Now, American Express has changed the pricing for adding authorized users (AUs) to its Platinum card. Previously, a key benefit of the authorized user option was that a cardholder could give up to three other people access to the American Express Global Lounge Collection which includes Centurion Lounges and Delta SkyClubs (when flying on Delta). The Amex Platinum Card comes with a hefty annual fee of $695 and, until recently, the three authorized users could be added for $175 (just under $60 each).
 
To reduce crowding in lounges, Amex has increased the AU fee to $195
for each authorized user. With this increase, a cardholder who lists a spouse and two children as authorized users will now pay $585 for adding them for, with the $595 annual fee, a total annual fee of $1280. For that family of four, this is a price hike of more than $400.
 
This increase will affect different households in different ways. Ms. Optimizer and I travel together and use lounges frequently, so it makes sense for me to remain an AU on her platinum card. Our two children are also authorized users, but they rarely fly anywhere so they can easily be dropped as AUs going forward. The net change for us will be a $20 increase in cost for about the same level of lounge usage. But, of course, many cardholders from households who have been able to take advantage of adding three authorized users for $175 are going to be very unhappy. They will have to choose between dropping some AUs, paying $195 for each AU, or perhaps having AUs get their own Amex Platinum card.


The post-COVID rebound of air travel has led to a lot of crowding in lounges and airlines and credit card issuers have responded by raising costs, enacting new policies to restrict access, or both. It will be interesting to see how this increase in fees for authorized users of the Platinum card will unfold over the coming months. It is likely that there will be more changes to come but we will be keeping an eye on them for you.
 
Lounge access remains an attractive benefit for many travelers but changes in fees and rules for access are altering the value proposition for some while leaving others unaffected. As we create Travel Rewards Optimizer plans for our clients, we will keep these changes in mind for clients who are interested in lounge access to ensure they get the greatest value.


We are ready to help you turn your routine credit card spending into the travel of your dreams
By Frank McBride September 4, 2026
In case you missed them, here is your "one-stop shopping" for posts from the past week. For some, recent changes with the Resy restaurant reservation platform might limit dining options when using the credit. Learn more here . Perhaps your next US domestic award flight should be booked through . . . Air France. Check out why . The Amex Platinum card might have the highest annual fee for mass marketed cards. Find out if the benefits are worth it for my household here . Hope you have a great Labor Day weekend!! We are ready to help you turn your routine credit card spending into the travel of your dreams.
By Frank McBride September 3, 2026
A walk through one household's use of the Amex Platinum card
By Frank McBride August 28, 2026
For some domestic flights, Air France might save transferable miles
By Frank McBride August 27, 2026
Recent changes in the Resy reservations platform might limit use of the Amex dining credit
By Frank McBride June 25, 2026
Changes are a mixed bag but Hyatt regulars won't be happy
By Frank McBride June 5, 2026
Some good news in points and miles (and one warning)
By Frank McBride May 29, 2026
A change in favor of airline passengers (for a change)
By Frank McBride May 19, 2026
The Autograph Journey's transfer partner list grows slowly but steadily
By Frank McBride April 29, 2026
Points and miles free up the travel budget for pilsner, paprika, and pastizzi*
By Frank McBride April 23, 2026
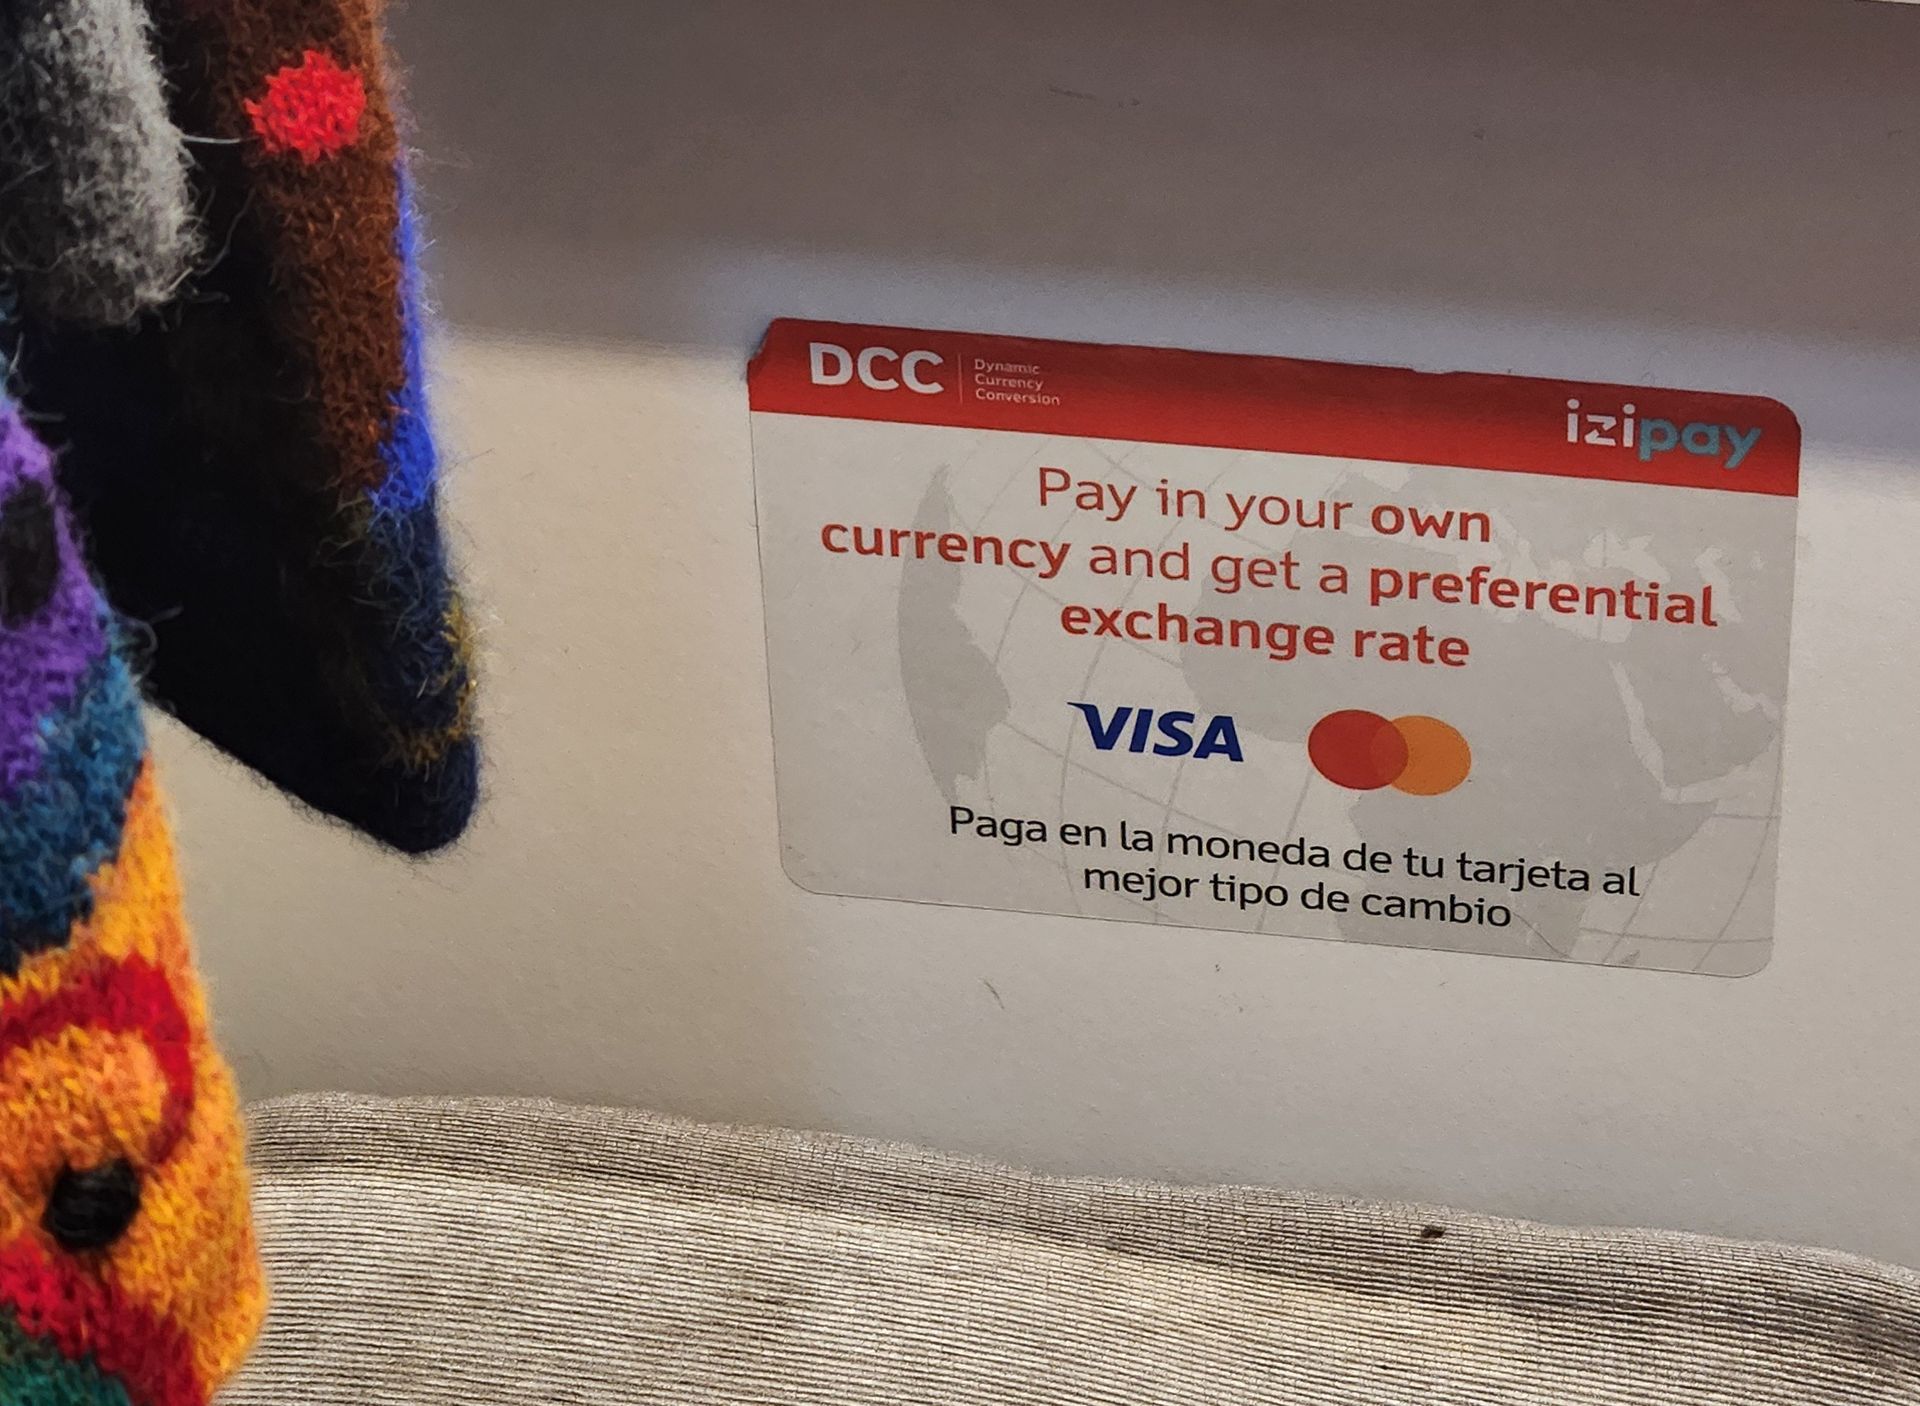
As the summer travel season approaches, this is a friendly reminder to avoid "dynamic currency conversion" (DCC) when making credit card purchases outside of your home country. DCC gives you the option of selecting a payment amount in your home currency rather than in the local currency. Typically, when presented with a credit card reader at a shop or restaurant, the touch screen will show purchase amounts in the local currency and in US dollars (for those with American credit cards) and you have the opportunity to choose. I have been seeing these “offers” for several years now and have learned, after doing a little mental math, they are almost always a bad deal for the purchaser. When presented with a credit card reader, I always choose to pay the amount shown in local currency rather than the amount shown in US dollars. During a recent trip, I was making purchases in Euros, Hungarian Forints, and Czech Korunas. From what I could tell, the option of paying in dollars inflated the cost of the purchases around an average of five percent (5%). Once, a card reader screen acknowledged that making the purchase in dollars added an eight percent (8%) fee. Even a credit card with a foreign transaction fee (which you should avoid using when traveling abroad) would have added only three percent (3%) to the tab. Currency games aside, Visa and MasterCard offer reasonable exchange rates when you choose to pay in the local currency. Upon returning home, our credit card statements showed exchange rates that were quite close to market rates. It is reasonable and fair for the credit card issuers make a fraction of a percent here and there as they are performing a service and accepting currency risk (although very briefly). But, claiming to offer a “preferential” rate to pad their bottom line is disingenuous. Because exchange rates are reasonable, using credit cards while traveling abroad is still worthwhile for a points and miles program as long as you avoid cards with foreign transaction fees. Travel oriented cards can offer 2X and 3X spending bonuses for transportation and restaurants to give you a leg up on saving money and accumulating points or miles for your next vacation.